Flip Funding Private Lending NetworK
Be the lender.
Not the landlord.
Fund one real estate loan at a time. See the borrower, the property, the numbers and the exit before you put a dollar in. We've been on the borrower side of this business since 2012 and funded over $1 billion in investor loans. Now we're opening up the other side of the table.
Every loan you review shows you
01. Who's borrowing and what they've done before
02. What the property is worth today and after the work
03. How much equity sits in front of your money
04. The budget, the timeline and how you get paid back
05. What happens if the plan breaks
Don't like what you see? Pass. No pressure, no penalty.
No commitment. No money moves on a call. Ever.
$1B+
in real estate investor loans funded
Since 2012
broker, correspondent and direct lender
Best Overall
Hard Money Lender
Business.org
Best for
First-Time Investors
Benzinga, Best Hard Money Lenders
$1B+
Lending through every market since our first close in 2013in real estate investor loans funded
Since 2012
broker, correspondent and direct lender
Best Overall
Hard Money Lender
Business.org
Best for
First-Time Investors
Benzinga, Best Hard Money Lenders
Straight talk first
Most private money pitches lead with a number. I'd rather lead with the real question.
The real question isn't "how much can I make?" It's "what happens to my money if the borrower doesn't pay?"
I've sat in every seat at this table. I started as an investor flipping houses. I've been the broker, the correspondent and the direct lender. I've watched good deals close and I've watched bad ones fall apart. Most of the time you can see the problem coming if you know where to look.
That's what this network is built on. You don't get dropped into a blind fund. You see one loan, the actual property, the actual borrower, the actual numbers. You ask whatever you want. Then you decide.
Private lending can be a great way to put capital to work in real estate without fixing toilets or chasing rent. It also carries real risk, and I'm going to show you exactly where that risk lives. If that sounds like the kind of conversation you want, let's talk.
Rod Stanback
Founder, Flip Funding
What this actually is
One lender. One loan. Your call.
The Private Lending Network matches people who have capital with individual real estate loans that Flip Funding has sourced, structured and reviewed. We're starting deal by deal, on purpose. No fund, no pool, no money sitting somewhere waiting to be put to work.
1
You see the whole loan
Borrower, property, valuation, budget, terms and exit. If something's missing, it gets answered before you decide, not after.
2
You choose yes or no
Nothing funds automatically. Nothing reinvests on its own. Every loan is its own decision, and passing costs you nothing.
3
Your position is documented
The lender of record, the collateral, the lien and who services the loan are spelled out in the closing documents and checked against title before funds move.
The deals we fund
Out of the box doesn't mean out of bounds.
Banks want a clean file, a stabilized property and 60 days. A lot of good real estate doesn't look like that. Value add flips. Ground up builds. Bridge loans that need to close this week. Deals with a story that takes an experienced lender to read.
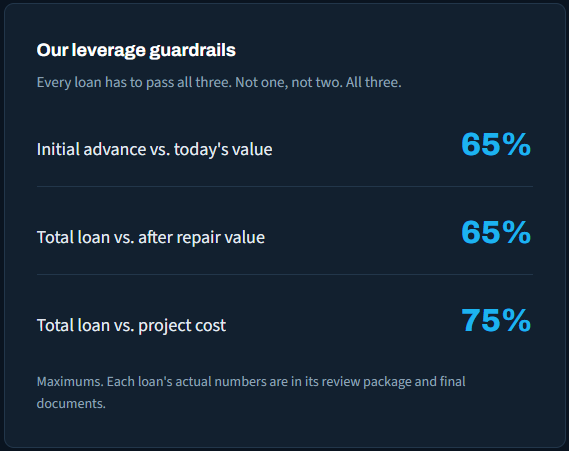
That's where we live. It's also why we're strict about leverage. A creative structure still has to make sense on paper, with real equity in front of the lender.
Is this you?
This isn't for everybody. That's the point.
A good fit if you
Have capital you can leave committed for the life of a loan, usually around 12 months
Want real estate exposure without managing tenants, contractors or rehabs
Like to look under the hood before you commit
Understand a payment can run late and principal can be lost
Have a CPA, attorney or advisor you trust, or are willing to get one
Not a fit if you
Need a guaranteed return. Nobody honest can give you one.
Might need this money back on short notice
Are thinking about using emergency savings, tax money or funds you can't afford to lose
Want somebody else to make the decision for you
Are chasing the highest rate on the internet
How your capital is protected
Six layers between your money and a loss.
No single safeguard does the job. Stacked together, they make the loan a lot harder to break. Every one gets verified on every loan, not assumed.
Borrower equity in front of you
Our leverage limits mean the borrower has real money at stake. If the property has to be sold, they absorb the first hit, not you.
A recorded lien on the property
The loan is secured by a mortgage or deed of trust on the real estate, with lien position confirmed through title before closing.
Title insurance
Covers specified title problems under the policy, like an old lien nobody caught. It's protection against title defects, not against a bad deal.
Property insurance
Required coverage on the asset, with the lender's interest noted, so a fire or storm doesn't wipe out your collateral.
Controlled construction draws
Rehab money goes out after work is done and checked, not all up front. Your capital follows the progress.
13+ years of underwriting
Every deal goes through our Profitable Pairing Process: borrower, property, budget and exit reviewed by people who've seen what kills deals.
Here's what none of this does.
It doesn't guarantee repayment. Real estate backing gives you rights and a cushion. It doesn't make loss impossible. Anyone who tells you otherwise is selling you something. We'd rather you walk in with your eyes open.
The deals we fund
Here's what equity does when a deal goes wrong.
Say you fund a $300,000 loan on a property worth $500,000. Then the borrower defaults and the property has to be sold. Here's how your principal holds up as the sale price drops.
Hypothetical illustration only. Not an actual loan, forecast or guarantee. Excludes accrued interest and other claims, and a zero gap doesn't mean full recovery of everything owed.
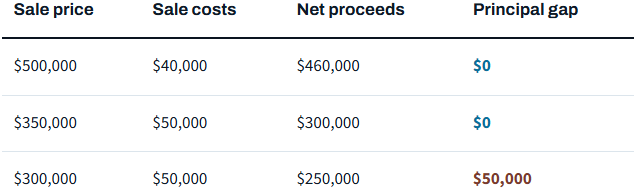
The property can drop 30% and the lender's principal is still covered in this example. Drop it 40% and there's a hole. That's why leverage is the first thing we look at, and the first thing you should too.
The process
From first call to first payment.
STEP 1
Fit call
20 minutes. Your goals, your comfortable range, your timing, your questions.
STEP 2
Capital profile
Tell us what you like: loan size, markets, property types. Complete eligibility review.
STEP 3
Loan review
When a matching loan comes through, you get the full package. Ask anything.
STEP 4
Decide and close
Yes or pass. A yes closes through title with signed documents and verified wiring instructions.
STEP 5
Servicing and payoff
Payments, reporting and borrower follow up handled under the loan documents until payoff.
The risks, plainly
What can go wrong, and what we do about it.
The borrower stops paying
We reach out fast, then work toward a cure, a documented workout or enforcement under the loan documents. Recovery can take time and cost money.
The market drops
Equity is your cushion. The guardrails exist so a softer market eats borrower equity before it touches your principal. A deep enough drop still can.
Your money is tied up
You can't pull out mid loan. A default or slow sale can keep capital committed past maturity. Only lend money you can leave alone.
All your eggs in one loan
One lender, one loan means one property carries your outcome. Many lenders spread capital across several loans over time.
Fraud or a mistake at closing
Identity checks, title review and verified wiring instructions cut this down. Never wire money based on an email alone. Call us on a number you already know.
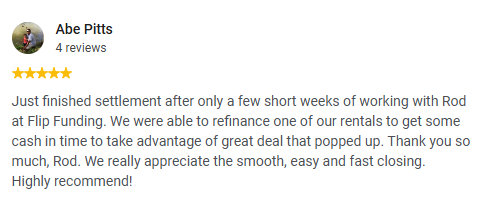
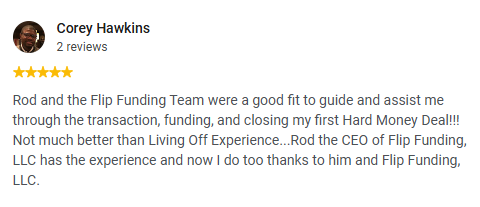
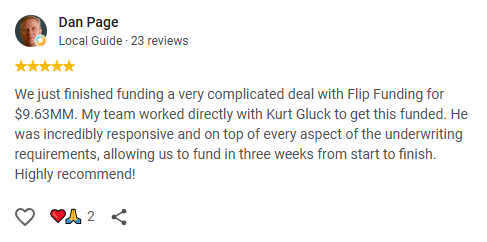
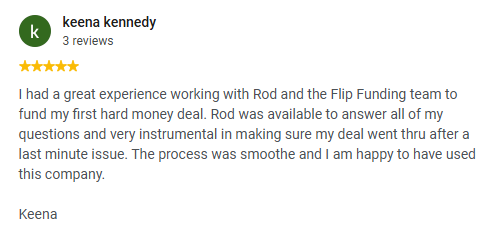
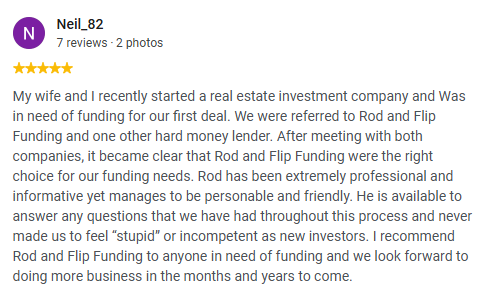
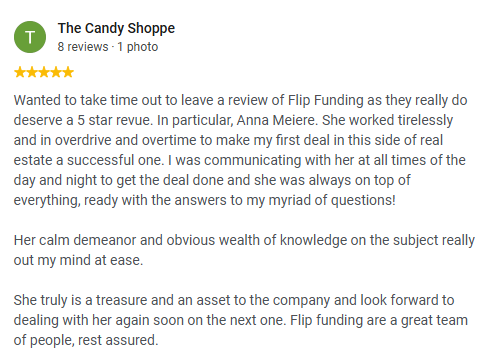
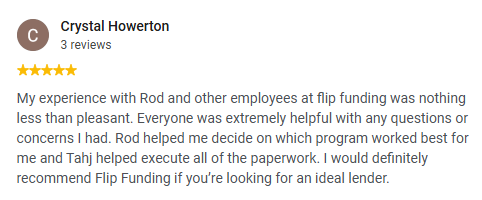
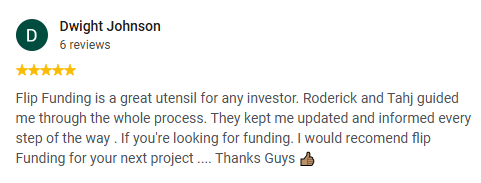
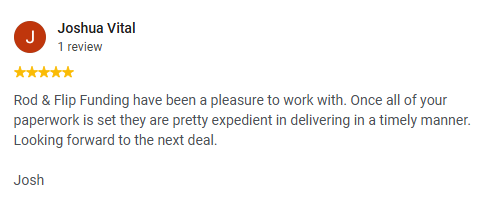
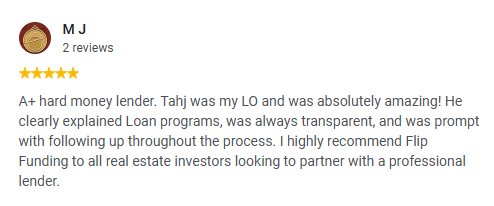
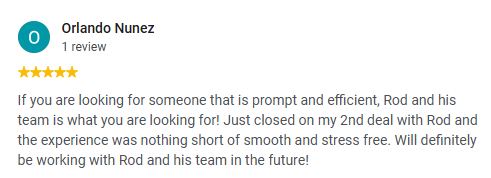
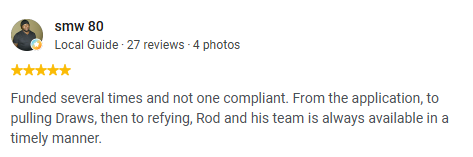
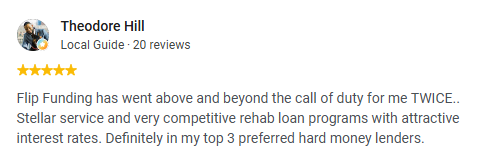
In their words
Over a decade of investors who trusted us with their deals.

Who's behind this
An investor who became a lender. Not the other way around.
Rod Stanback started investing in real estate in 2009. In 2012 he founded Flip Funding to give investors the kind of lender he wished he'd had: one that understands the deal, tells you the truth fast, and actually closes.
Since then Flip Funding has grown from broker to correspondent to direct lender, funding fix and flip, bridge, ground up construction, DSCR rental and commercial loans for investors nationwide.
$1B+
funded
2012
founded
3 seats
broker, correspondent, direct lender
broker, correspondent, direct lender
Questions
The stuff people actually ask.
How much do I need to get started?
It depends on the loan. Since one lender funds one whole loan, the amount matches the specific deal. On the fit call we'll talk about the range you're comfortable with and the loan sizes we typically see. That conversation commits you to nothing.
What kind of return can I expect?
Each loan has its own rate, term and payment schedule, and you'll see all of it in the review package before you decide. We won't quote you a blanket number on a web page. The rate a borrower pays isn't automatically what lands in your account after fees and servicing, so we walk through your actual numbers on every deal.
How is my money protected?
Borrower equity in front of you, a recorded lien on the property, title and property insurance, controlled draws and our underwriting. Every safeguard gets verified on every loan. Together they reduce risk a lot. They don't guarantee repayment, and we won't pretend they do.
What happens if the borrower stops paying?
The servicing side reaches out, then works toward a cure, a documented workout, an extension or enforcement under the loan documents and state law. That can take time and money. A lender may recover everything, part of what's owed, end up with the property, or take a loss. You'll know who makes those calls before you fund.
Can I get my money back early?
Plan on your capital being committed for the full term, usually around 12 months. A borrower paying off early is different from you being able to withdraw. And if a loan defaults, your money can stay tied up past maturity.
Do I need to be an accredited investor?
Eligibility depends on the final structure of each opportunity. We'll walk you through the requirements before you see any loan. Filling out the form here doesn't confirm or deny eligibility.
Is my money pooled with other investors?
No. We're starting with one lender per loan. No fund, no fractional pieces, no automatic reinvestment. You pick each loan or you pass.
Can I use an LLC, trust or retirement account?
Possibly. It depends on the structure and the rules for your entity or account. If you're thinking about retirement money, talk to your custodian and a tax advisor before you move anything.
How does Flip Funding get paid?
Our role and compensation on each loan are disclosed in the final documents, including who pays each fee and how it affects what you receive. Ask us about it directly. You should always know how the people on the other side of the table make money.
Does booking a call commit me to anything?
No. The call is for both of us to figure out if this fits. Never send money because of a form, a call or a presentation. Funds only move through a title closing after you've reviewed the loan and signed final documents.
Got one we didn't cover? Bring it to the call. That's what it's for.
Next step
20 minutes. No pitch deck pressure. Just answers.
We'll talk through how the network works, what you'd review on a real loan, and whether it makes sense for you. If it doesn't, I'll tell you. That's a good outcome too.
No commitment and no money moves on the call
Talk to someone who has funded these loans for 13+ years
Walk away with a clear yes, not yet, or not for me
Prefer to talk now? (844) 998-2949 or [email protected]
Submitting this doesn't commit you to anything. Please don't send financial documents here.
Copyright © 2026 Flip Funding. All Rights Reserved.
+1 (844) 998-2949 [email protected] flipfunding.com
TRANSFORMING THE PRIVATE LENDING EXPERIENCE THROUGH SPEED, TRANSPARENCY, AND CREATIVE STRUCTURE. WE EMPOWER PROFESSIONAL BROKERS TO CLOSE MORE COMPLEX DEALS.